(Kiemsat.vn) – Giving gifts to customers on holidays, Tet, and customer conferences to serve production and business activities, businesses must make invoices, calculate declaration and pay value added tax (VAT). ) as selling goods to customers.
On November 28, 2017, the General Department of Taxation issued Official Letter 5483/TCT-DNL to answer related tax policies on this issue. As follows:
– When giving gifts to customers on holidays, New Year, and customer conferences to serve production and business activities, enterprises must make invoices, calculate and pay value added tax (VAT) like sales. goods for customers.
– In case the enterprise has incurred gift giving to customers to serve production and business activities, the customer does not need to get an invoice, then at the end of each day, the enterprise shall make a common VAT invoice with the amount shown. on the total line of the statement, sign and keep the copy for the buyer, other copies are circulated as prescribed (regardless of the value of the gift).
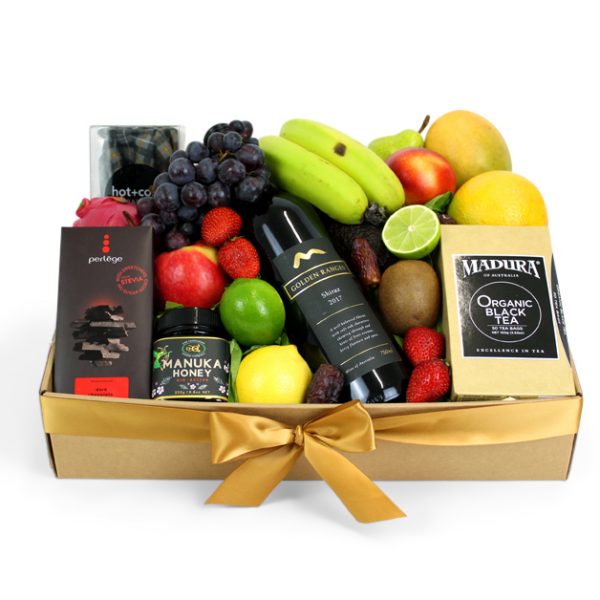
Illustrations (internet)
In addition, the General Department of Taxation guides the making of invoices as follows:
– In case, when selling goods or providing services of VND 200,000 or more each time, the buyer does not receive an invoice or does not provide his/her name, address, and tax code (if any), he/she must still issue an invoice and record it in writing. clearly “buyer does not take invoice” or “buyer does not provide name, address, tax code.
– For products, goods and services used for promotion in accordance with the law on commerce, an invoice must be made, the name and quantity of the goods must be written on the invoice, clearly stating that they are promotional or advertising goods. , sample goods and comply with the guidance of the law on VAT.
– For goods and services used to give, offer, donate, exchange or pay wages on behalf of employees, a VAT invoice (or sales invoice) must be made. calculate VAT as invoices for selling goods and services to customers.”
Source: Kiemsat.vn
📋 BÀI VIẾT LIÊN QUAN CÓ THỂ BẠN QUAN TÂM:
- 📝 How is the act of buying and selling illegal invoices handled?
- 📝 Value added tax increase to 12%: Millions affected
- 📝 Guidance on publishing business registration information, declaring tax information and deadlines for amending and supplementing online business registration dossiers
- 📝 Legal provisions on CIT incentives SUMMARY OF CASE OF CIT INCENTIVES INCLUDING LEGAL PROVISIONS
- 📝 Declare transfer tax on futures contract
📞 LIÊN HỆ VỚI CHÚNG TÔI ĐỂ ĐƯỢC TƯ VẤN:
HÃNG LUẬT DHP
HÃNG LUẬT DHP trụ sở chính: Tòa nhà The Manor 2, Số 89 Nguyễn Hữu Cảnh, P. Thạnh Mỹ Tây, Tp. Hồ Chí Minh
HÃNG LUẬT DHP Văn phòng tư vấn tại Hà Nội: VA03A – 9 Villa Hoàng Thành, P. Kiến Hưng, Tp. Hà Nội
HÃNG LUẬT DHP Văn phòng tư vấn tại Phú Quốc: Số 115B Trần Hưng Đạo, Đặc khu Phú Quốc, tỉnh An Giang
HÃNG LUẬT DHP Văn phòng Miền Tây Nam Bộ: Tầng 5 Tòa nhà Blossom Building, Số 153Q Trần Hưng Đạo, P. Ninh Kiều, TP. Cần Thơ.
Hotline: 0868335186
Email: luatdhp@gmail.com
Website: dhplaw.vn
Facebook: HÃNG LUẬT DHP